This is one of those decisions where the Swiss banking system operates with the same reliability as an SBB train—usually impeccable, until construction slows the line. And right now, you’re staring at the construction zone.
Let me save you the suspense: the answer isn’t either extreme. It’s smarter than both.
Why Your Brain Is Screaming “Invest in the Nice Car”
There’s a voice in your head that sounds very reasonable. It says things like: “If I buy a 30,000 CHF car, it’ll last me 10 years. That’s only 3,000 CHF per year. The 4,000 CHF beater will die in 18 months and cost me 2,000 CHF in repairs. The math is obvious.”
I get it. I really do. And mathematically, there’s a version of this argument that works.
But here’s what that voice isn’t telling you: a car is not an investment. It’s a depreciating asset that burns cash the moment you drive it off the lot. As one sharp commenter on the original thread put it, “Ein Auto ist keine Investition”—a car is no investment—unless you happen to own a classic 300SL, which you don’t.
New cars in Switzerland lose 20–35% of their value in the first four months alone. That 30,000 CHF car will be worth maybe 22,000 CHF by spring 2027. You’re not investing, you’re renting transportation with extra steps.
The Real Cost of Owning a Car in Switzerland
Before we even get to the purchase price, let’s talk about what happens after you buy. The soaktuell.ch analysis of Swiss household budgets found that even a paid-off second car costs 500–700 CHF per month on a full cost basis—that’s Vehikelsteuer (vehicle tax), parking, MFK (roadworthiness test), service, tires, fuel, insurance, and depreciation combined.
Run that math forward:
- 3,000 CHF car: 500–700 CHF/month × 12 months = 6,000–8,400 CHF/year just to keep it moving
- 30,000 CHF car: Same running costs, plus higher insurance premiums and faster depreciation = 9,000–12,000 CHF/year
That’s why Swiss new car sales have dropped by nearly a third over the past decade. People figured out that dumping cash into a vehicle is the financial equivalent of throwing it into a wood chipper—it’s just slower and smells better.
What’s Actually in Your Budget Range
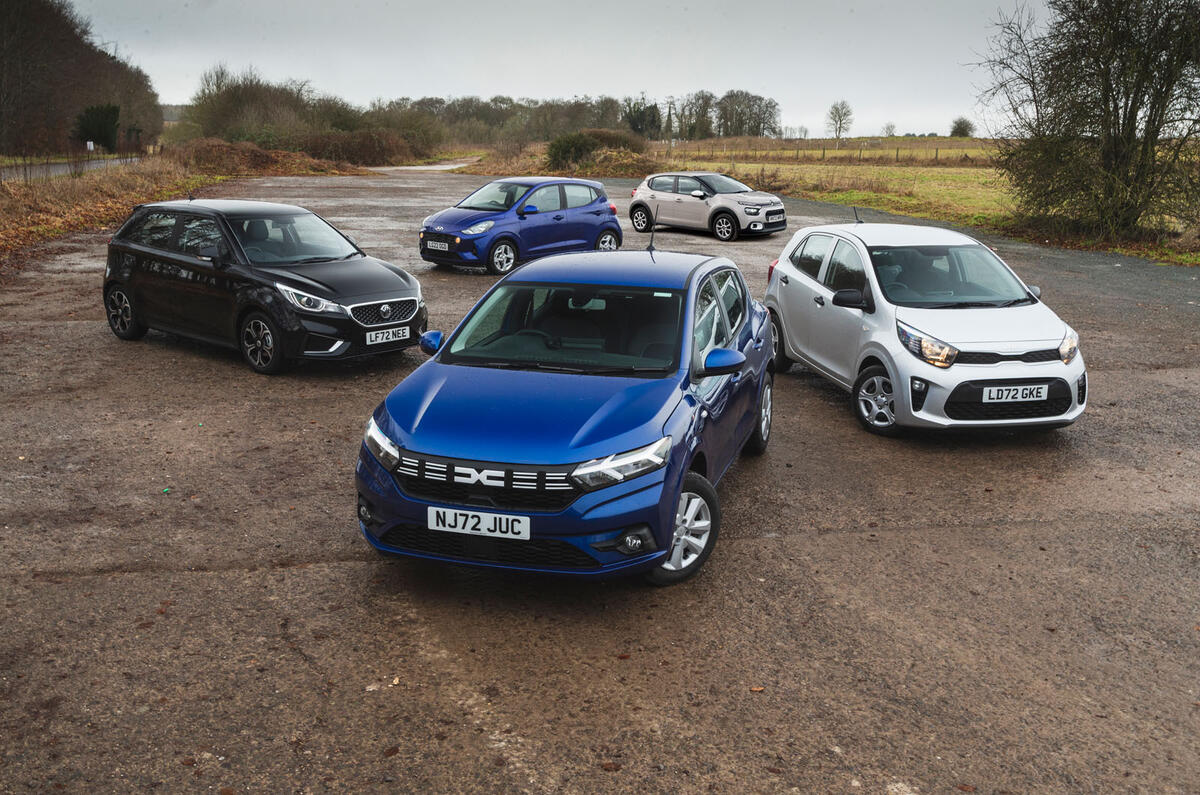
The 3,000–5,000 CHF bracket: You’re looking at early-to-mid 2000s Japanese hatches (Toyota Yaris, Honda Jazz, Nissan Micra), maybe a Volkswagen Golf IV or V with 180,000+ km. The good news: these are cheap to insure, cheap to fix, and parts are everywhere. The bad news: they’re old enough that rubber seals, suspension components, and water pumps start failing one by one, like a slow-motion game of whack-a-mole.
One commenter shared they picked up a Nissan Micra for 1,200 CHF and have been driving it happily for over a year, mostly for work and school commutes. They even got 2,000 CHF from insurance when a delivery driver dinged it, meaning the car actually made them money. That’s Team Shitbox energy, and honestly, I respect it.
The 30,000 CHF bracket: You’re now in nearly-new territory—a 2-3 year old Škoda Octavia, VW Golf, or Toyota Corolla with reasonable mileage. These will absolutely handle the Autobahn to Germany comfortably and reliably. But here’s the uncomfortable question: what else could you do with that 25,000 CHF difference?
At current rates, Swiss personal loans start around 3.95% APR with providers like PostFinance. If you’re financing the 30,000 CHF car, you’re adding interest to a depreciating asset—the financial equivalent of setting money on fire while standing in the rain.
The Opportunity Cost Nobody Mentions
Here’s where this decision gets interesting. You’ve got 2,500–3,000 CHF of monthly surplus. That’s not pocket change—that’s meaningful financial firepower.
Leveraging your cash flow for large purchases is about understanding what your money could be doing instead. That 25,000 CHF difference between the beater and the “reliable” car, if invested in a simple global ETF, could reasonably double over 10–12 years. Meanwhile, the 30,000 CHF car will be worth a third of that at the same point.
I’m not saying you should never buy a nice car. I’m saying you should understand what that choice actually costs.
The Middle Path: The 10,000–15,000 CHF Sweet Spot
Here’s the move I’d actually recommend: find a well-maintained, 5–8 year old Japanese or Czech car with full service history and around 80,000–120,000 km. You can find solid options in the 10,000–15,000 CHF range that will:
- Handle Zurich-to-Berlin trips without breaking a sweat
- Still have reasonable OEM parts availability
- Depreciate more slowly than a new car (you’re past the steep part of the curve)
- Cost less to insure than a premium badge
Before buying any used car in Switzerland, get a Gebrauchtwagencheck (used car inspection)—AMS, TCS, and independent garages all offer pre-purchase inspections for 200–400 CHF. That’s the cheapest insurance you’ll ever buy.
The Decision Framework That Actually Works
Here’s the honest truth: your first car is a learning experience. As one commenter pointed out, buying cheap first means “you’ll make mistakes and get smarter. It’s usually more comfortable when the car wasn’t expensive.” You’ll scrape a curb, misjudge a parking space, or leave something in the boot that shouldn’t be there. Would you rather learn that lesson on a 4,000 CHF car or a 30,000 CHF one?
But you’ve also got legitimate long-distance needs. Family in Germany isn’t a weekend trip—it’s a commitment.
My recommendation: start with a 5,000–8,000 CHF car that’s been inspected by a professional. Drive it for 12–18 months. Learn what you actually need from a vehicle. Bank the 2,000 CHF+ monthly surplus you’re saving versus the 30,000 CHF option. Then, when you’ve got 18 months of real driving data and a fatter savings account, upgrade if you still feel the need.
What about leasing? In most cases, avoid it. Leasing in Switzerland locks you into a contract for something that’ll depreciate anyway. The only scenario where leasing makes sense is if you’re a business owner who can deduct the costs—not for private use.
The Bottom Line
Your instinct to ask this question before dropping serious cash already puts you ahead of most people making impulse purchases at the Autohaus (car dealership). The fact that you’re thinking about this systematically—posting your actual numbers, and seeking advice? That’s the financial equivalent of checking your mirrors before a lane change—it shows you’re paying attention.
A car should serve your life, not drain it. Start modest, stay flexible, and let your future self, with more savings and more clarity about what you actually need, make the bigger call.
Want more help navigating Swiss financial decisions? Check out this deep dive on whether buying property is actually better than investing, or this breakdown of why Swiss rent vs. buy decisions often come down to assumptions, not just math.